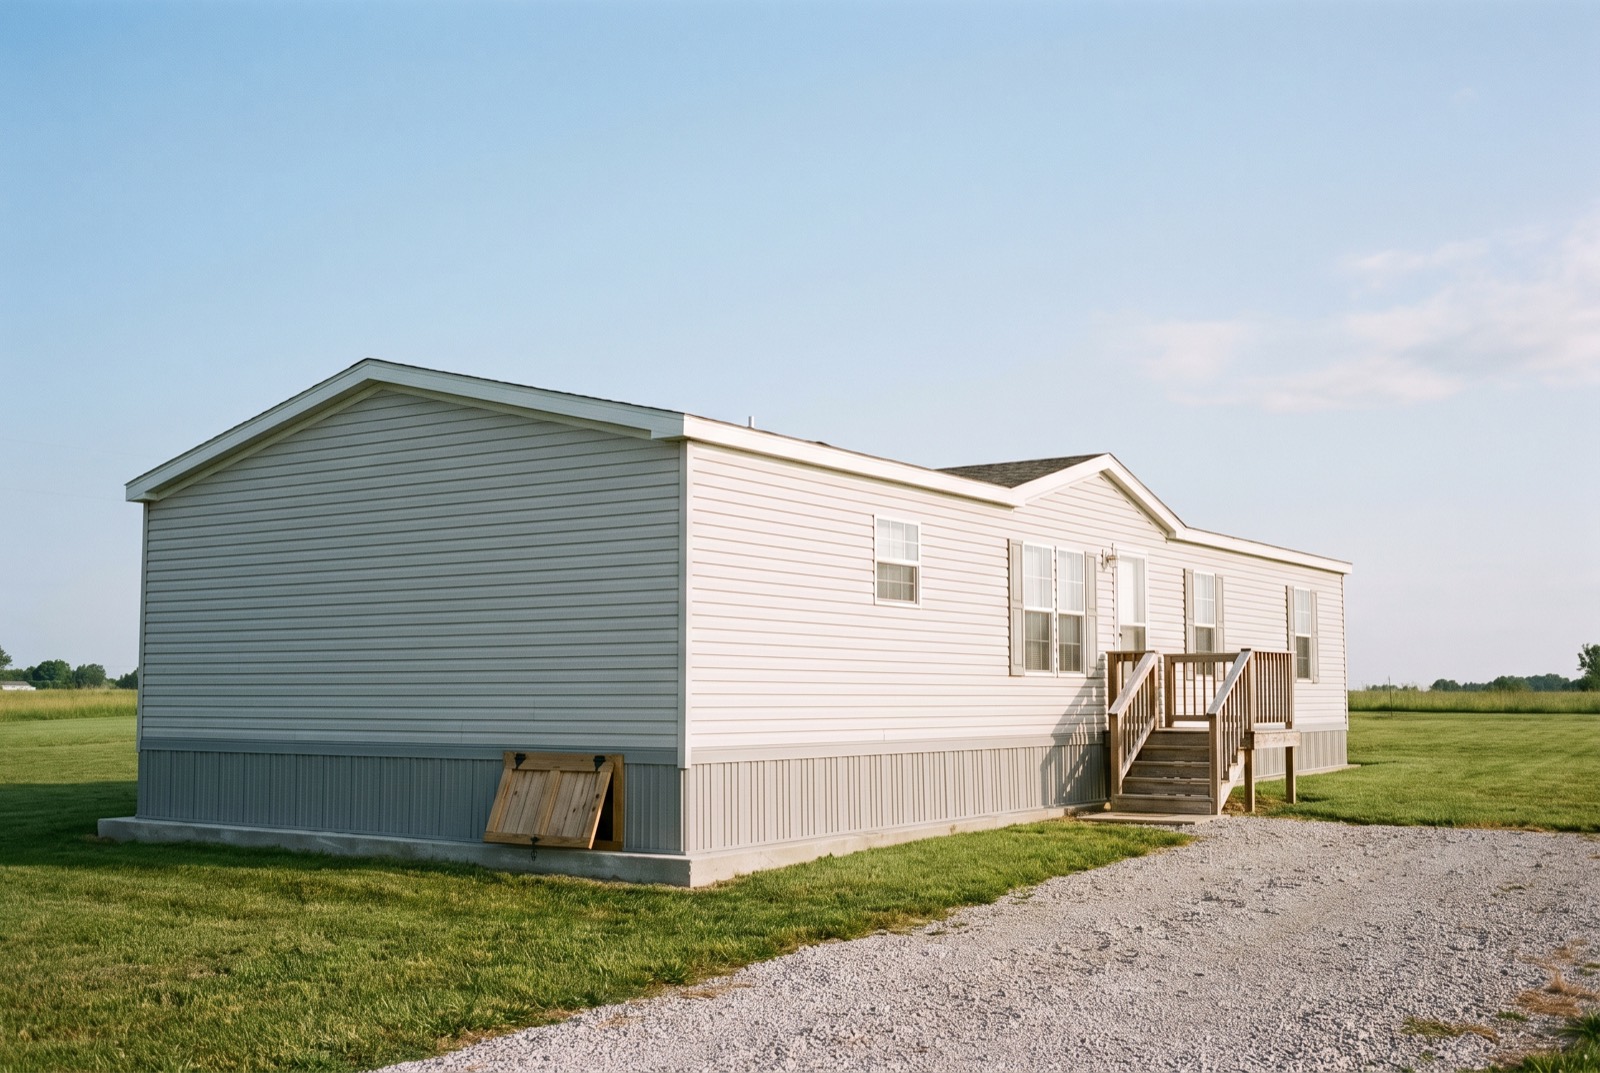
What does an FHA lender need for a manufactured home foundation?
For an FHA mortgage on a manufactured home, a permanent foundation that meets the applicable requirements is part of whether the property is eligible. The lender usually asks for a certification from an engineer licensed in the state where the home sits, tied to HUD's Permanent Foundations Guide for Manufactured Housing.
A borrower's preapproval does not replace this property paperwork. Ask your lender for the foundation condition in writing before you order anything.
Does the home need a full basement?
You cannot tell a compliant foundation by one feature. A basement, a finished perimeter, or skirting does not settle the question by itself. The engineering question is how the home is actually supported and secured, measured against the lender's criteria.
A long history on the same site does not settle it either. Describe what is there when you contact us, but do not choose repairs based on appearance alone.
Can an earlier certification be reused?
Sometimes. HUD's handbook describes situations where a certification from a previous FHA-insured mortgage may be used, subject to conditions. Whether it works for your file is your lender's decision.
If you have an older report, send it to the lender and to us. It is useful background, but it is not automatically acceptable and not automatically useless. Read about the report itself in what is a HUD engineering report.
What about additions and alterations?
If the appraisal identifies an addition or alteration, the lender must make sure it is addressed in the certification. Tell us about porches, enclosed rooms, decks, and earlier foundation repairs when you request the inspection, with dates if you know them.
What if the foundation needs work?
Ask what the findings are before arranging repairs. Depending on the condition and the assignment, the next step may be more information, a repair design, completed work, or another review. Confirm what the original quote covers and what would cost extra.
A paid inspection is not a promise of a favorable result. The engineer reports what the conditions support, and the lender separately decides whether the documents satisfy its requirement. We cannot promise approval or eligibility.
Which documents should you gather?
- The property address and state.
- The lender's written foundation condition.
- Any earlier engineering report.
- Notes on additions, alterations, or repairs.
- Photos of the HUD label and data plate, if you have them.
- Who can give access, and your report deadline.
If a record is missing, say so. See missing HUD label or data plate for what to do. Our FHA and HUD foundation inspection service handles the engineering side.
What should you send us?
Send the address and the lender's condition. We reply within one business day.